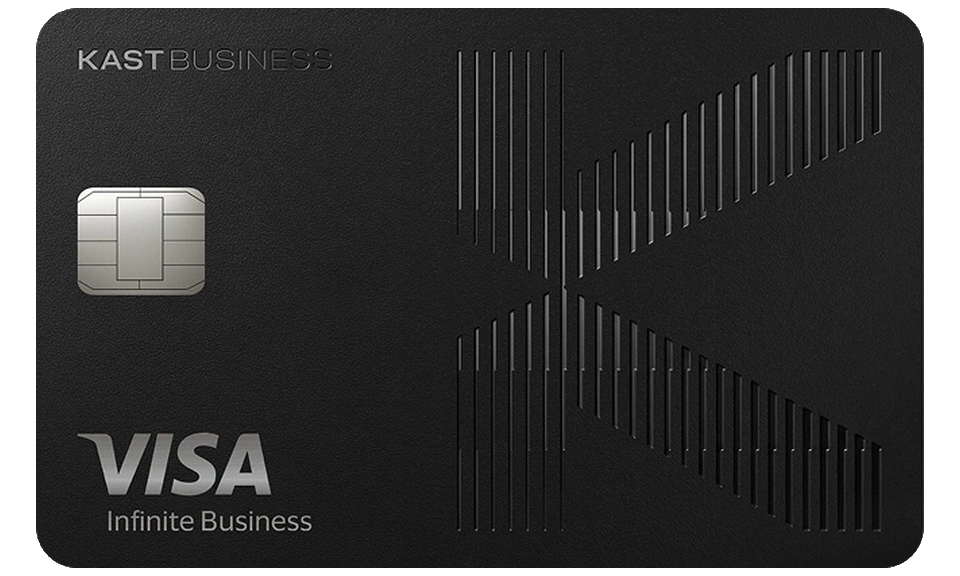
Kast Card Review: Capped cashback, steep paid-tier fees

Kast Card offers 1.5% to 3% cashback on eligible spending, with monthly caps that vary by tier. Standard is the practical starting point for USD spenders because it has no annual subscription. Premium and Private need much heavier use to justify their fees, and redeemed cashback only offsets future card spending.
At a glance
| Feature | Kast Card terms |
|---|---|
| Card type and network | Visa credit card; credit line secured by your deposited KAST balance |
| Purchase APR | 0% across Standard, Premium and Private |
| Annual subscription | Standard: $0; Premium: $1,000; Private: $10,000 |
| Eligible-spend cashback | Standard: 1.5%, up to $30/month; Premium: 2%, up to $200/month; Private: 3%, up to $1,200/month |
| Cashback redemption | Offsets future card spending; cannot be withdrawn as cash |
| Availability | US, Latin America, United Kingdom and EEA; country and regional availability must be confirmed in the KAST app or with support |
| Verification | Government-issued ID and source-of-funds checks; proof of address may be required |
| Non-USD spending | 0.5% to 1.75% FX fee, plus $0.10 per purchase under $25 |
Rates & fees
Compare tiers
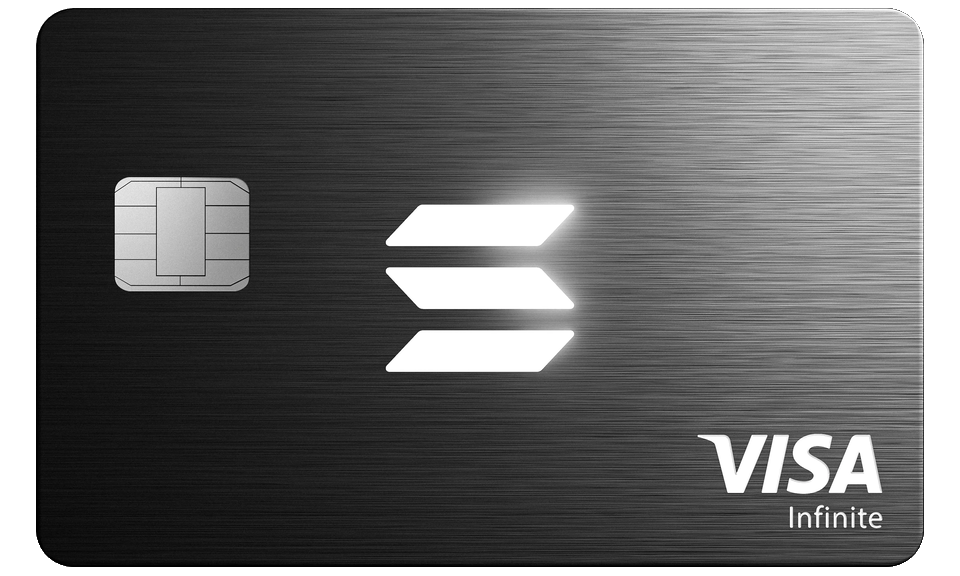
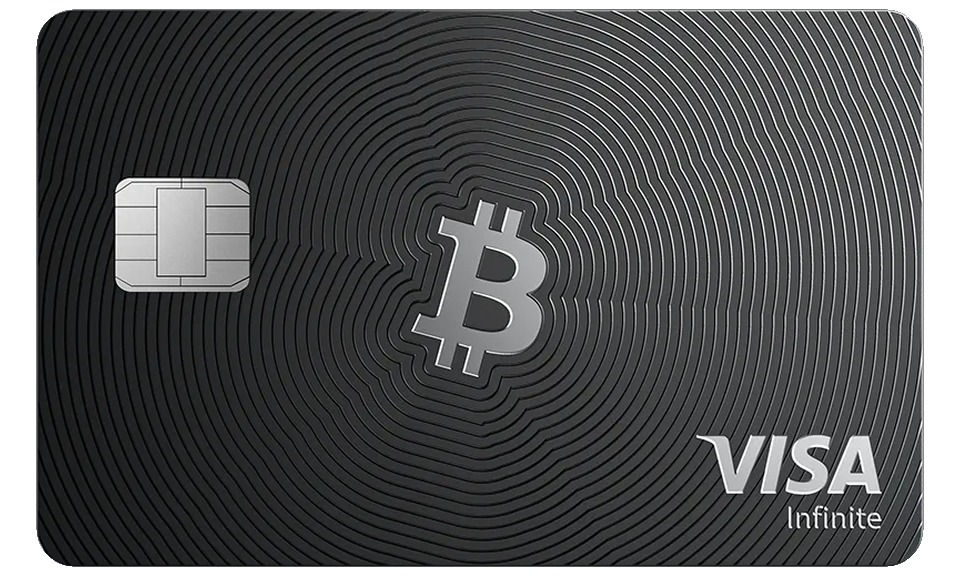
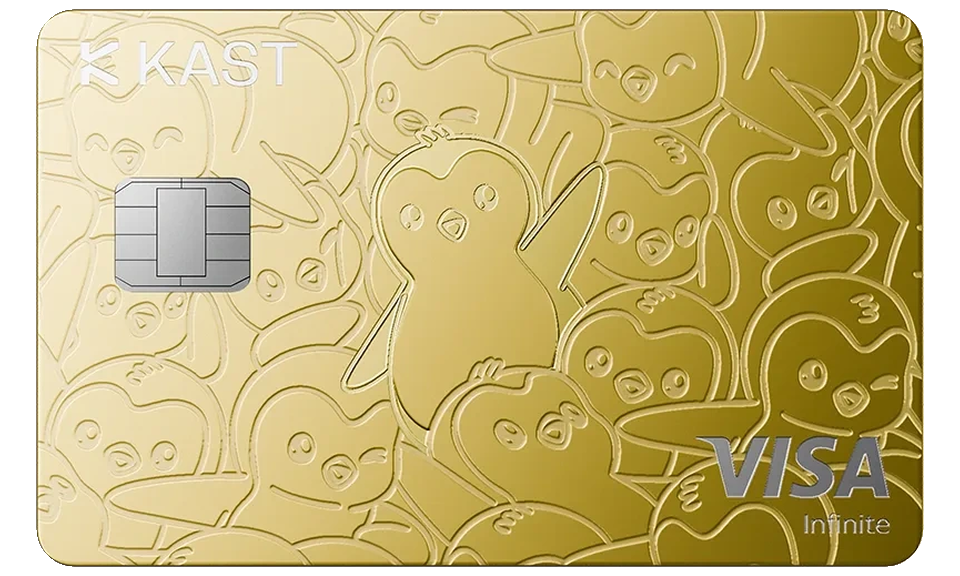
Pros & Cons
How the Kast Card works
Kast Card is a Visa credit card offered in Standard, Premium and Private tiers. Each tier has a credit line secured by your deposited KAST balance and a 0% purchase APR. You need to commit funds to support the credit line, so the practical decision is whether the rewards and benefits justify that commitment and the applicable fees.
All three tiers have no fixed daily or monthly card-spending cap beyond available funds. That is separate from cashback: you can reach your monthly reward cap even while you still have money available to spend.
Standard offers an instant virtual card for digital payments, with a $2 issuance fee in some regions. All three tiers include physical card options.
Who should choose it, and who should skip it
Standard is the most straightforward starting point for eligible shoppers who mainly make USD purchases and want to avoid an annual subscription. Its cashback cap is reached at $2,000 of eligible monthly spending, so it suits modest reward expectations rather than a plan to earn cashback on every dollar indefinitely.
Premium can suit heavier spenders who can use its higher cashback cap and eligible Visa Infinite V2 benefits. Private is a narrower fit for very high spenders who can justify a $10,000 annual commitment. The higher rate alone is not a sufficient reason to upgrade.
Look elsewhere if you need rewards you can withdraw as cash, regularly use ATMs, or mainly make small non-USD purchases. Those usage patterns run into the redemption restriction or recurring transaction costs.
Cashback, KAST Points and Reserve are separate benefits
The headline percentages describe different things. Standard earns 1.5% spending cashback, Premium earns 2%, and Private earns 3%, each subject to its own monthly cap. Premium also earns 1% in KAST Points on eligible spending, while Private earns 2% in KAST Points. Keep those points separate when comparing cash savings.
Redeemed cashback reduces later card spending and cannot be withdrawn as cash. That makes it useful for an ongoing KAST user, but less flexible for someone who wants to move rewards out of the account.
Reserve is a separate earn program with stated reward rates of 8% for Standard, 10% for Premium and 12% for Private, under an offer ending July 1, 2027. These are not card-purchase cashback rates and should not be added to the spending rates.
Rewards and monthly caps
Cashback applies to eligible purchases. Cash withdrawals, transfers and other financial transactions are excluded. Once a tier reaches its cashback cap for the month, additional spending does not increase that month’s cashback.
Premium and Private membership fees are billed upfront and are non-refundable except where required by law. Compare the annual cost with the rewards you can actually use, rather than judging the tier by its percentage alone.
| Tier | Eligible-spend cashback | Monthly cashback cap | Monthly spend reaching cap | Additional eligible-spend points |
|---|---|---|---|---|
| Kast Standard Card | 1.5% | $30 | $2,000 | |
| Kast Premium Card | 2% | $200 | $10,000 | 1% in KAST Points |
| Kast Private Card | 3% | $1,200 | $40,000 | 2% in KAST Points |
Do the paid tiers cover their annual fees?
Consider a US user making $10,000 of eligible USD purchases every month for a full year. Standard reaches its $30 monthly cap, producing $360 of cashback over the year. Premium earns $200 monthly, or $2,400 annually. Subtracting Premium’s $1,000 annual membership leaves $1,400 of cashback value, which is $1,040 more than Standard before other costs.
At that same spending level, Private earns $300 monthly, or $3,600 annually. Its $10,000 membership exceeds that cashback by $6,400. For this shopper, Private needs substantial value from benefits beyond spending cashback to justify the price.
For a US user instead making $40,000 of eligible USD purchases every month for a full year, Private reaches its $1,200 monthly cap. Annual cashback is $14,400, leaving $4,400 after its $10,000 membership. Premium remains capped at $2,400 annually, or $1,400 after membership. Private therefore provides $3,000 more cashback value after membership in this scenario.
These examples assume the stated spending repeats every month and redeemed cashback is fully used for later purchases. They exclude points, Reserve, card issuance, ATM use and all other transaction costs. Uneven monthly spending can produce a different result because the caps apply monthly.
Kast Card fees and limits
USD purchases and card top-ups carry no provider percentage fee across the three tiers. Non-USD transactions and cash withdrawals have separate charges, so an annual subscription does not remove the main usage fees.
The same ATM limits apply to Standard, Premium and Private: $250 per withdrawal, $750 daily and no more than three withdrawals in a rolling 24-hour period. Paying for a higher tier does not increase these limits.
| Fee or limit | Amount | When it applies |
|---|---|---|
| Standard annual subscription | $0 | Standard membership |
| Premium annual subscription | $1,000 | Billed upfront each year; non-refundable except where legally required |
| Private annual subscription | $10,000 | Billed upfront each year; non-refundable except where legally required |
| Provider top-up percentage fee | 0% | All three tiers |
| USD purchase percentage fee | 0% | All three tiers |
| Foreign exchange fee | 0.5% to 1.75% | Non-USD transactions on all tiers |
| Small non-USD purchase fee | $0.10 | Additional fee on non-USD purchases under $25, all tiers |
| Insufficient-balance decline fee | $0.50 | Transactions declined for insufficient balance, all tiers |
| ATM withdrawal fee | $3 plus 2% | All tiers; non-USD withdrawals may also incur FX charges |
| ATM amount limits | $250 per withdrawal; $750 daily | All tiers |
| ATM frequency limit | Three withdrawals | Per rolling 24-hour period, all tiers |
| Standard virtual issuance | $2 in some regions | Check the app before confirming issuance |
Where fees and benefit conditions change the value
Standard vs Premium vs Private: which tier fits?
All three tiers cover the US, Latin America and EEA, with country and regional availability subject to confirmation in the app or with KAST Support. A valid government-issued ID and source-of-funds checks are required; proof of address may also be needed.
Choose a tier based on eligible monthly spending and benefits you expect to use. The same purchase APR, FX range and ATM terms apply across the collection, so upgrading primarily changes the membership cost and reward package.
| Card | Annual subscription | Best-fit spending profile | Main trade-off | Markets |
|---|---|---|---|---|
| Kast Standard Card | $0 | USD spenders seeking modest cashback without a subscription | $30 monthly cashback cap; redemption only offsets later purchases | US, Latin America, EEA; confirm local availability |
| Kast Premium Card | $1,000 | Heavier eligible spenders who can also use eligible travel and purchase benefits | Upfront annual fee; $200 monthly cashback cap | US, Latin America, EEA; confirm local availability |
| Kast Private Card | $10,000 | Very high eligible spenders who can justify a larger benefit package | Substantial upfront fee; $1,200 monthly cashback cap | US, Latin America, EEA; confirm local availability |
Start with the tier your spending can justify
Standard can be a sensible entry point for an eligible USD spender who accepts the cashback cap and plans to keep using KAST. Premium deserves a closer look when recurring eligible spending and usable benefits can cover its annual fee. Private requires a much stronger spending case.
If your main priorities are frequent cash withdrawals, non-USD everyday purchases or cash rewards you can transfer out, the shared fees and redemption restriction are reasons to consider another option. Confirm local availability before committing funds or paying for membership.
Kast Card FAQ
Is the Kast Card worth it?
Standard can be a good fit for eligible USD spenders seeking 1.5% cashback without an annual subscription, subject to a $30 monthly cap. Premium and Private make more sense when spending and usable benefits justify annual fees of $1,000 and $10,000, respectively.
How much cashback does the Kast Card pay?
Standard earns 1.5% on eligible spending up to $30 monthly, Premium earns 2% up to $200 monthly, and Private earns 3% up to $1,200 monthly. Cash withdrawals, transfers and other financial transactions do not earn cashback; redeemed cashback offsets later card spending and cannot be withdrawn as cash.
What fees does the Kast Card charge abroad?
All three tiers charge 0.5% to 1.75% on non-USD transactions, plus $0.10 for non-USD purchases under $25. ATM withdrawals cost $3 plus 2%, with possible additional FX charges on non-USD withdrawals.
What are the Kast Card ATM limits?
Standard, Premium and Private each allow ATM withdrawals of up to $250 per transaction and $750 daily, with a maximum of three withdrawals in a rolling 24-hour period.
Which countries is the Kast Card available in?
Kast Card coverage includes the US, Latin America and the European Economic Area. Availability varies by country and region, so confirm your location in the KAST app or with KAST Support before applying.
Does the Kast Card require KYC?
KAST requires a valid government-issued ID and source-of-funds checks. Proof of address is required conditionally.